BNM holds OPR at 2.75% but analysts eye a hike to 3% in early 2027
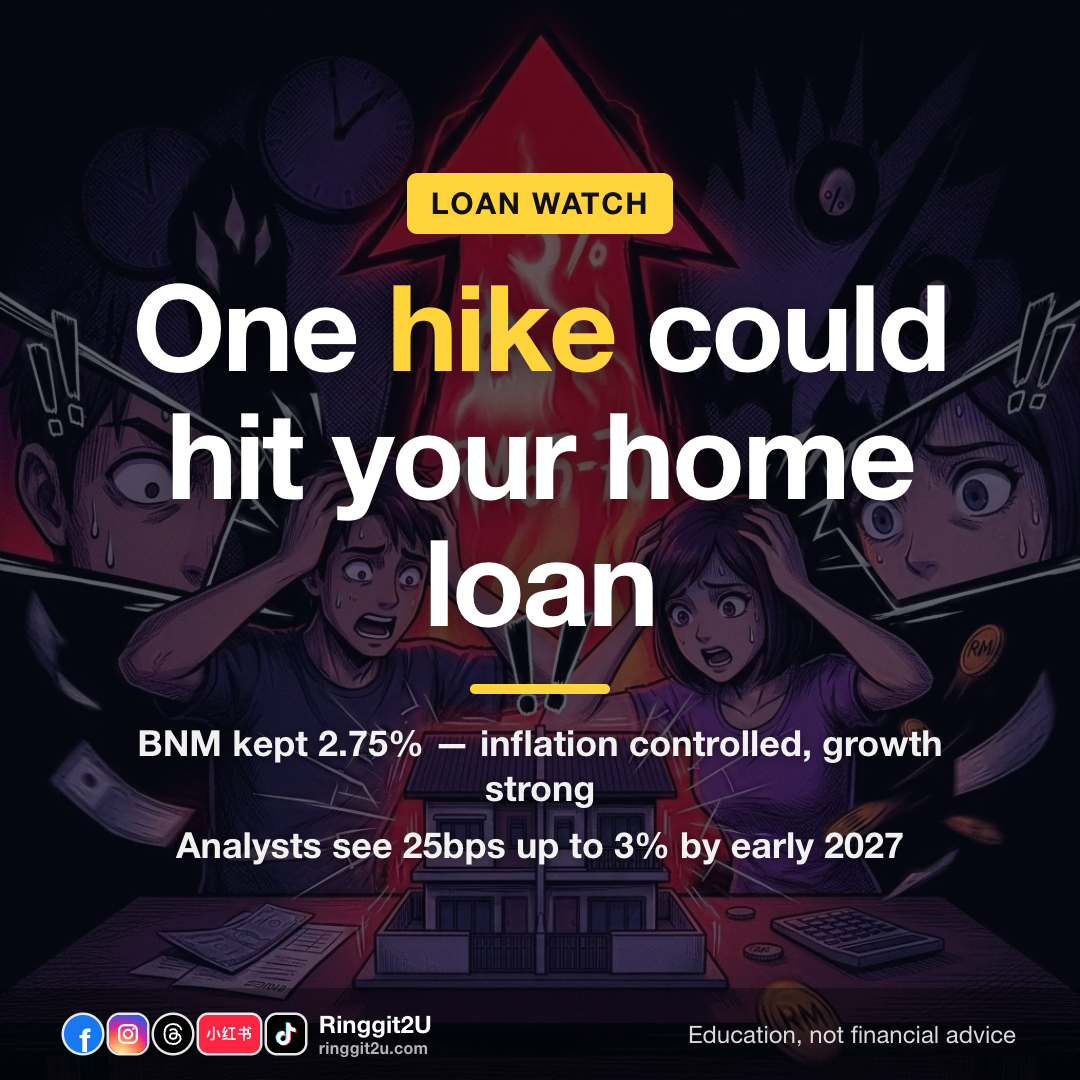
BNM held the OPR at 2.75% for the eighth straight meeting, but analysts expect a 25 basis point hike to 3% in the first quarter of 2027.
What happened1/6 BNM keeps OPR at 2.75% to support growth
Bank Negara Malaysia (BNM) maintained the Overnight Policy Rate (OPR) at 2.75% at its sixth and final MPC meeting of 2026.
Finance Minister II Datuk Seri Amir Hamzah Azizan said inflation remains under control and GDP growth is strong, giving businesses room to keep growing with stable financing conditions.
The real numbers2/6 The key rate figures to watch
2.75%Current OPR rate3%Projected OPR (Q1 2027)8Consecutive unchanged meetingsThe OPR has been unchanged for eight consecutive meetings since the 3 September 2026 decision was the seventh in the streak.
Market analysts expect a 25 basis point increase to 3% in the first quarter of 2027, driven by resilient growth and elevated inflation projections.
On the US side, Fed official Collins backed gradual rate hikes, citing inflation and jobs data that warrant tighter policy.
- 01/01
3% Projected OPR (Q1 2027) The key rate figures to watch Projected OPR (Q1 2027)
How it works3/6 How the OPR affects your home loan
The OPR is Bank Negara's policy rate, not the interest rate you pay directly.
Banks set their Base Rate (BR) or Standardised Base Rate (SBR) based on the OPR.
If the OPR rises, banks typically raise their base rates, which increases the interest cost on floating-rate loans.
Most home loans in Malaysia are floating-rate. Most hire-purchase car loans are fixed-rate and are not affected by OPR changes.
How it affects your wallet4/6 What a 25 basis point hike means for your monthly payment
A rise in the OPR from 2.75% to 3% means a 25 basis point increase in the interest rate on floating-rate loans.
e.g. For a RM500,000 home loan with 30 years remaining, a 25 basis point rate increase could raise your monthly instalment by approximately RM65 to RM70.
Check your loan agreement to see if your rate is floating or fixed. Only floating-rate loans will see this change.
Why it matters5/6 Why fixed deposits might earn more
When the OPR rises, banks often increase the interest rates on fixed deposits (FDs) to attract funds.
A report by NST noted that a potential OPR hike could boost banks' Net Interest Margin (NIM), with Public Bank set to gain most.
If you have spare cash, compare FD rates across banks before locking in a long-term deposit. Rates may improve if the hike happens in early 2027.
What to watch6/6 Next steps for borrowers
Review your home loan statement to confirm your current interest rate and whether it is floating or fixed.
Monitor BNM's Monetary Policy Committee (MPC) announcements for the first meeting of 2027.
If you have a floating-rate loan, budget for a potential slight increase in monthly payments starting in Q1 2027.
Questions people ask
Will my car loan interest rate go up if the OPR rises?
Most hire-purchase car loans in Malaysia have fixed interest rates for the entire tenure. Therefore, an OPR hike usually does not change your car loan instalment. Check your loan agreement to confirm.
How soon will my home loan rate change after the OPR hike?
Banks typically adjust their Base Rate (BR) or Standardised Base Rate (SBR) shortly after BNM announces an OPR change. Your monthly instalment will then be recalculated in the next payment cycle.
Should I refinance my home loan now?
Refinancing involves fees and legal costs. It is only beneficial if the new interest rate is significantly lower than your current rate. Consult a licensed financial adviser or your bank for personal advice.