Medical Insurance Rose 9.1% in 2025, 15x Faster Than Clinic Visits
Health insurance prices rose 15 times faster than clinic visit costs in 2025, and 24% of cardholders already switched or cancelled.
What happened1/5 DOSM: health insurance prices jumped 9.1% in 2025 while clinic visits barely moved
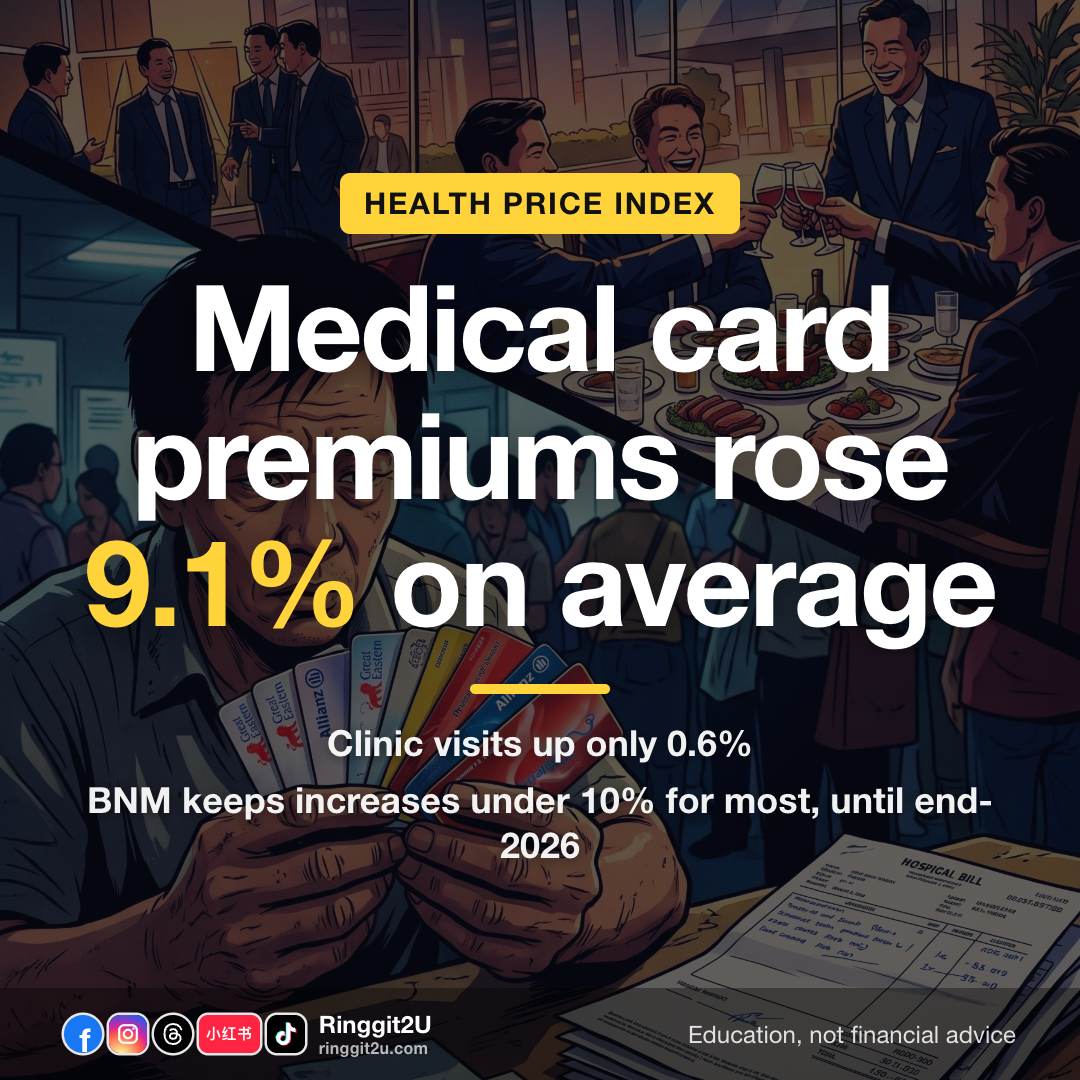
The Department of Statistics Malaysia published its Annual Health Price Index 2025 on 10 November 2026. Health insurance prices rose 9.1% in 2025, after not moving at all in 2024.
A clinic visit cost just 0.6% more. That means insurance premiums climbed 15 times faster than the cost of actually seeing a doctor. Across all healthcare, prices rose 3.0%, up from 1.3% in 2024.
The real numbers2/5 Insurance rose 9.1% while every treatment category stayed under 5%
9.1%health insurance price rise, 20250.6%clinic visit price rise, 20253.0%all healthcare prices, 2025Medicines were the priciest treatment category at 4.5%, still only half the insurance jump. Dental visits and hospital stays each rose 1.5% or less.
On average, medical insurance coverage that cost RM100 in 2024 cost RM109.10 in 2025. Your own increase could be higher or lower depending on your plan and age.
Category 2025 price change Health insurance 9.1% Medicines 4.5% Dental visits ≤1.5% Hospital stays ≤1.5% Clinic visits 0.6% - 01/03
9.1% health insurance price rise, 2025 Insurance rose 9.1% while every treatment category stayed under 5% health insurance price rise, 2025
How it affects your wallet3/5 One in four cardholders already switched, cut cover or cancelled
The RinggitPlus Malaysian Financial Literacy Survey 2026 asked 1,096 people who hold both life insurance or takaful and a personal medical card. 24% switched to a cheaper plan, reduced coverage, or cancelled in the past 12 months because of rising costs. Another 58% kept their existing plan.
If you do not have a medical card at all, you are not alone: 36% of everyone surveyed said they have none. Another 20% rely only on a medical card from their employer, which usually ends the day they leave the company.
e.g. A plan that cost RM100 a month in 2024 cost about RM109 a month in 2025. Over 12 months, that is roughly RM109 extra for the same coverage.
Why it matters4/5 BNM's under-10% premium cap protects you through your next renewal
Since December 2024, Bank Negara Malaysia has required insurers to keep yearly premium increases under 10% for most policyholders. That cap is in force right now and runs until 31 December 2026. Your next renewal, if it falls before that date, cannot jump more than 10% under the rule.
After 2026, yearly increases no longer have to stay under 10%. The DOSM data shows the pattern the cap was meant to address: insurance prices sat flat in 2024, then jumped 9.1% in 2025 — the first full year under the cap. Without the cap, insurers can set their own pace again.
- 02/03
0.6% clinic visit price rise, 2025 Insurance rose 9.1% while every treatment category stayed under 5% clinic visit price rise, 2025
What to do, step by step5/5 Open your renewal notice today and work through these choices
A higher renewal notice does not have to mean cancellation. Work through these options before you sign or cancel.
If you rely only on your employer's medical card, start comparing personal plans now so you are not bare on your last day at work. If you have no medical card at all, the government-backed MediAsas plan opens to the public in January 2027 with indicative premiums of RM60 to RM550 a month. EPF members under 55 can pay MediAsas premiums from their Akaun Sejahtera savings, which hold 15% of every new contribution.
- Pull out your latest renewal notice and compare the new premium against what you paid in 2024. If the jump is close to 10%, you are at the BNM cap ceiling and have little room left before the rule expires on 31 December 2026.
- Call your insurer or agent and ask for a lower-tier plan with the same network hospitals. You may keep cover at a smaller sum insured.
- Ask about a deductible plan. You pay the first part of each hospital bill yourself, and the insurer pays the rest up to your limit. The trade-off is a lower monthly premium.
- If you have no personal medical card, start comparing plans now, including deductible options, so you are not caught without cover when the BNM cap lifts at the end of 2026. Check comparison tools on BNM's portal or ask your insurer for a list of available plans.
- 03/03
Insurance rose 9.1% while every treatment category stayed under 5% Monthly statement Health insurance 9.1% Medicines 4.5% Dental visits ≤1.5% Hospital stays ≤1.5% Clinic visits 0.6%
Questions people ask
Will my medical card premium go up more than 10% after 2026?
The BNM rule that keeps yearly increases under 10% for most policyholders runs until 31 December 2026. After that, insurers can set increases without that cap. The DOSM data records what already happened in 2025; it does not predict next year.
Can I use my EPF savings to pay for MediAsas?
Yes, if you are an EPF member under 55. MediAsas premiums can be paid from your Akaun Sejahtera savings, which receive 15% of every new contribution. The plan opens to the public in January 2027 with indicative premiums of RM60 to RM550 a month.
I only have my employer's medical card. What happens if I quit?
Employer medical cards usually end when you leave the company. The RinggitPlus 2026 survey found 20% of respondents rely only on an employer card. Start comparing personal plans before your last working day so there is no gap in cover.
Source: KWSP (EPF)The StarRinggitPlus